Working capital: where the cash is actually hiding
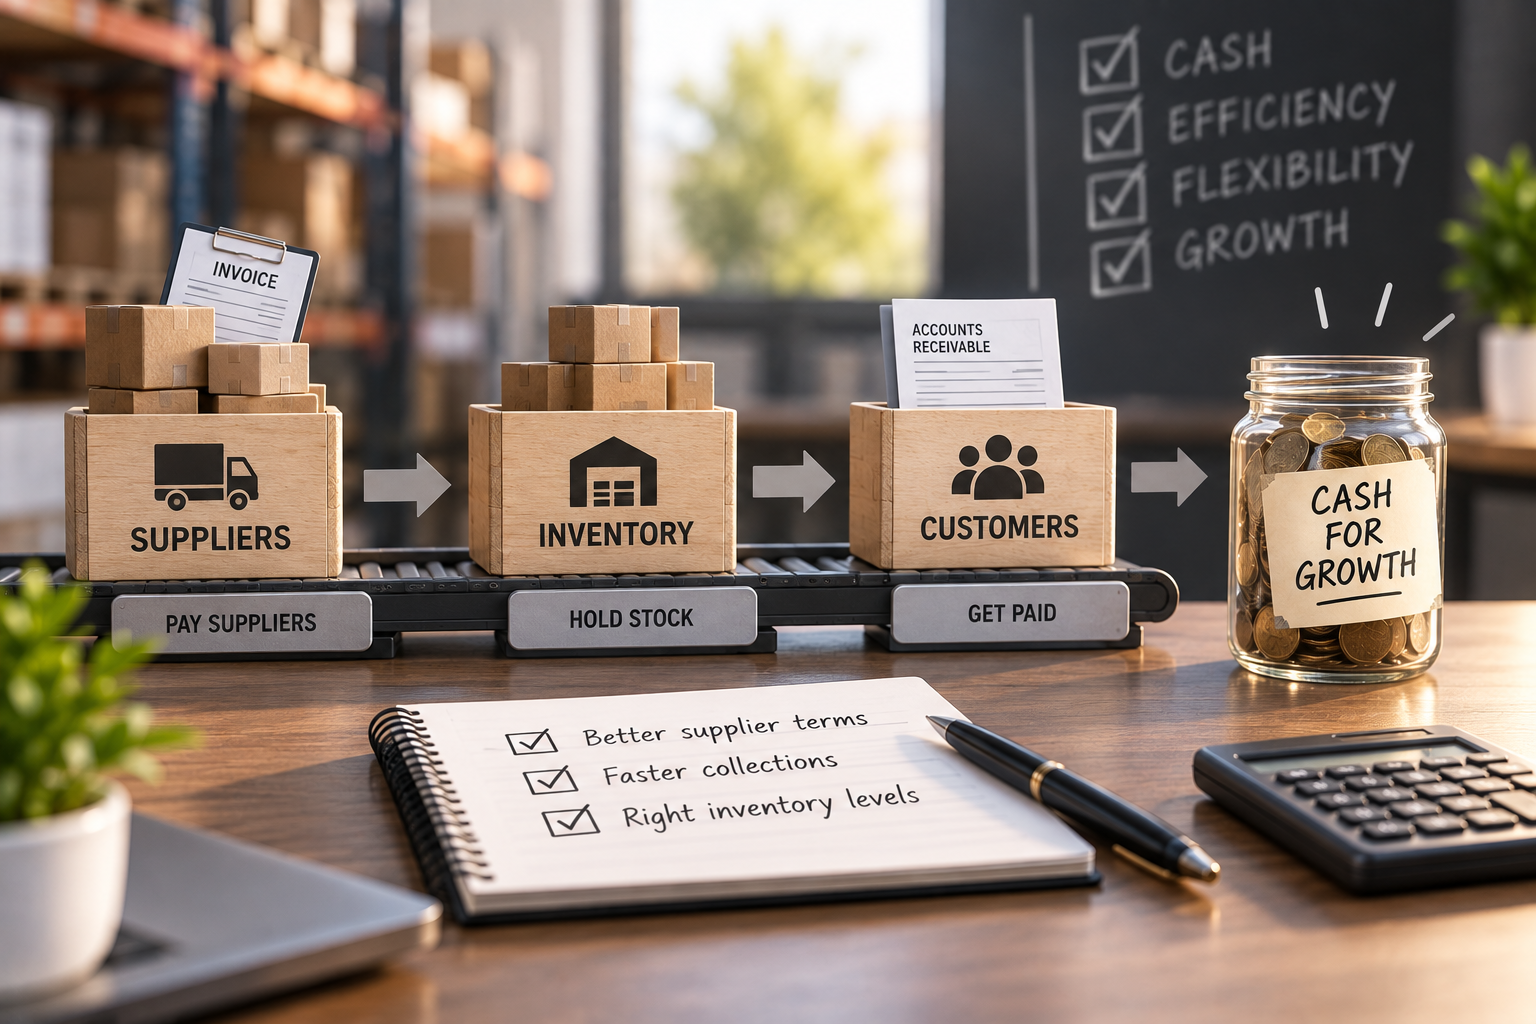
Before seeking a bigger credit line, look at the cash tied up between paying suppliers and getting paid by customers. Better terms, disciplined collections and tighter inventory can reduce the funding your growth needs.
In short
- Growth can absorb cash even when sales and margins look healthy.
- Measure the full journey from supplier payment to customer receipt, not just overdue invoices.
- Release cash deliberately: protect reliable suppliers, profitable customers and the stock you genuinely need.
A growing business can be profitable and still feel permanently short of cash. Orders increase, stock arrives, people do the work — and the money comes back weeks or months later. A credit line can bridge that gap, but it does not fix the reasons the gap keeps widening.
Before borrowing more, examine the cash already committed to the business. Customer terms, collections and inventory often deserve attention first. The objective is not simply to pay later and chase harder. It is to shorten the time between cash going out and coming back, without damaging the relationships and service that support growth.
Start with the cash journey, not the bank balance
For this review, focus on operating working capital: customer receivables plus inventory, less supplier payables. A service business may hold little stock, but substantial cash can still be tied up in work completed but not yet billed. Deposits and advance payments also affect how much funding the business needs.
Map one typical order from purchase or project start to final collection. When do you commit cash? When can you invoice? What has to happen before the customer approves payment? The delay may sit in production, sign-off or invoicing rather than in the finance team’s collections process.
A useful starting measure is the cash conversion cycle: inventory days plus customer payment days, less supplier payment days. Track the trend, but inspect the underlying balances too. An average can hide a large disputed invoice, seasonal stock build or a customer whose buying has recently slowed.
1. Set payment terms before the work starts
Payment terms are part of the commercial deal, not an administrative detail added after the price is agreed. A sale with a healthy margin can still put pressure on cash if you must buy materials now and wait several months for payment.
Look at new contracts and renewals first. Where commercially appropriate, ask for a deposit, invoice at agreed milestones or bill recurring services in advance. For bespoke orders, align customer payments with significant supplier commitments so you are not funding the entire job.
Make the payment mechanics explicit: the legal entity being billed, purchase-order requirements, invoice submission route and who signs off delivery. Agree how additional work will be approved and charged. Otherwise, a nominal 30-day term can become much longer while an invoice waits for missing paperwork.
Give sales teams clear boundaries for offering extended terms. Exceptions should have an owner and a visible cash cost, rather than becoming an unrecorded concession used to close the deal.
2. Remove the reasons invoices do not get paid
Separate receivables into three practical groups: not yet due, overdue without dispute, and blocked or disputed. Each needs a different response. Upcoming large payments may warrant confirmation that the invoice is approved. Overdue balances need a specific payment commitment. Disputes need someone with the authority to resolve the underlying issue.
Review the largest and oldest balances weekly, with a named owner and next action. Record promised payment dates and follow up when they slip. A generic reminder email is not a substitute for knowing whether the customer has accepted the invoice and scheduled payment.
Also check the delay between delivery and invoicing. If completed work sits unbilled for ten days, improving collections alone leaves that cash untouched. Prompt, accurate invoices with the required supporting evidence are often the simplest place to start.
3. Buy for demand, not for the unit-price discount
Inventory can look reassuring on a warehouse report while quietly consuming the overdraft. Review stock by item, age and expected demand, not just total value. Separate fast-moving essentials from slow movers, obsolete lines and stock reserved for orders that may no longer proceed.
Challenge purchasing quantities against realistic sales, supplier lead times and the service level customers need. A bulk discount is not necessarily a saving once storage, financing and the risk of write-downs are considered.
For excess stock, stop unnecessary replenishment first. Then assess returns, transfers, bundles or controlled clearance. Writing stock down recognises a loss; it does not itself release cash. Cash comes from selling or returning it, or avoiding the next purchase.
Do not cut every line equally. Running out of a critical component can delay a much larger customer payment. The aim is less unproductive stock, not the lowest possible stock balance.
4. Negotiate breathing room without exporting the problem
Compare agreed supplier terms with actual payment timing. Paying early without a worthwhile benefit may be avoidable; paying late without agreement creates a different risk. Seek explicit changes where needed, such as staged payments, smaller deliveries or terms better aligned with customer receipts.
Prioritise continuity with critical suppliers. A short-lived cash gain is poor value if it leads to restricted supply, higher prices or demands for payment upfront. Include any lost settlement discounts when evaluating longer terms.
Turn the review into a cash-release plan
Put a value and expected date against each realistic action, then feed it into a short-term cash forecast. Distinguish genuine cash release from accounting changes and avoid counting the same receipt twice.
For illustration, a business with £3.65 million in annual credit sales averages £10,000 a day. Reducing collection time by five days could release roughly £50,000, assuming steady sales and a consistent measurement basis. That is a reduction in funding tied up, not an extra £50,000 of profit or a saving that repeats every month.
Keep the weekly review focused: overdue and unbilled balances, broken payment promises, slow-moving stock and upcoming supplier commitments. Assign actions across sales, operations, purchasing and finance; finance cannot resolve every cause alone.
Use the revised forecast to judge the remaining funding need. Seasonal peaks, long production cycles and rapid growth may still justify a credit line. The better outcome is not necessarily no borrowing. It is borrowing for a clear business need rather than continually financing avoidable delays.
About the author
Azadeh Aghajani, FCA
Founder of Simora Advisory. Twenty years in senior finance — CFO of two private-equity-backed payments companies, CFO of Asset Servicing at BNY, and FP&A and pricing leadership at TSYS, Barclays and RBS. She qualified as a Chartered Accountant at PwC.