What buyers look for two years before you sell
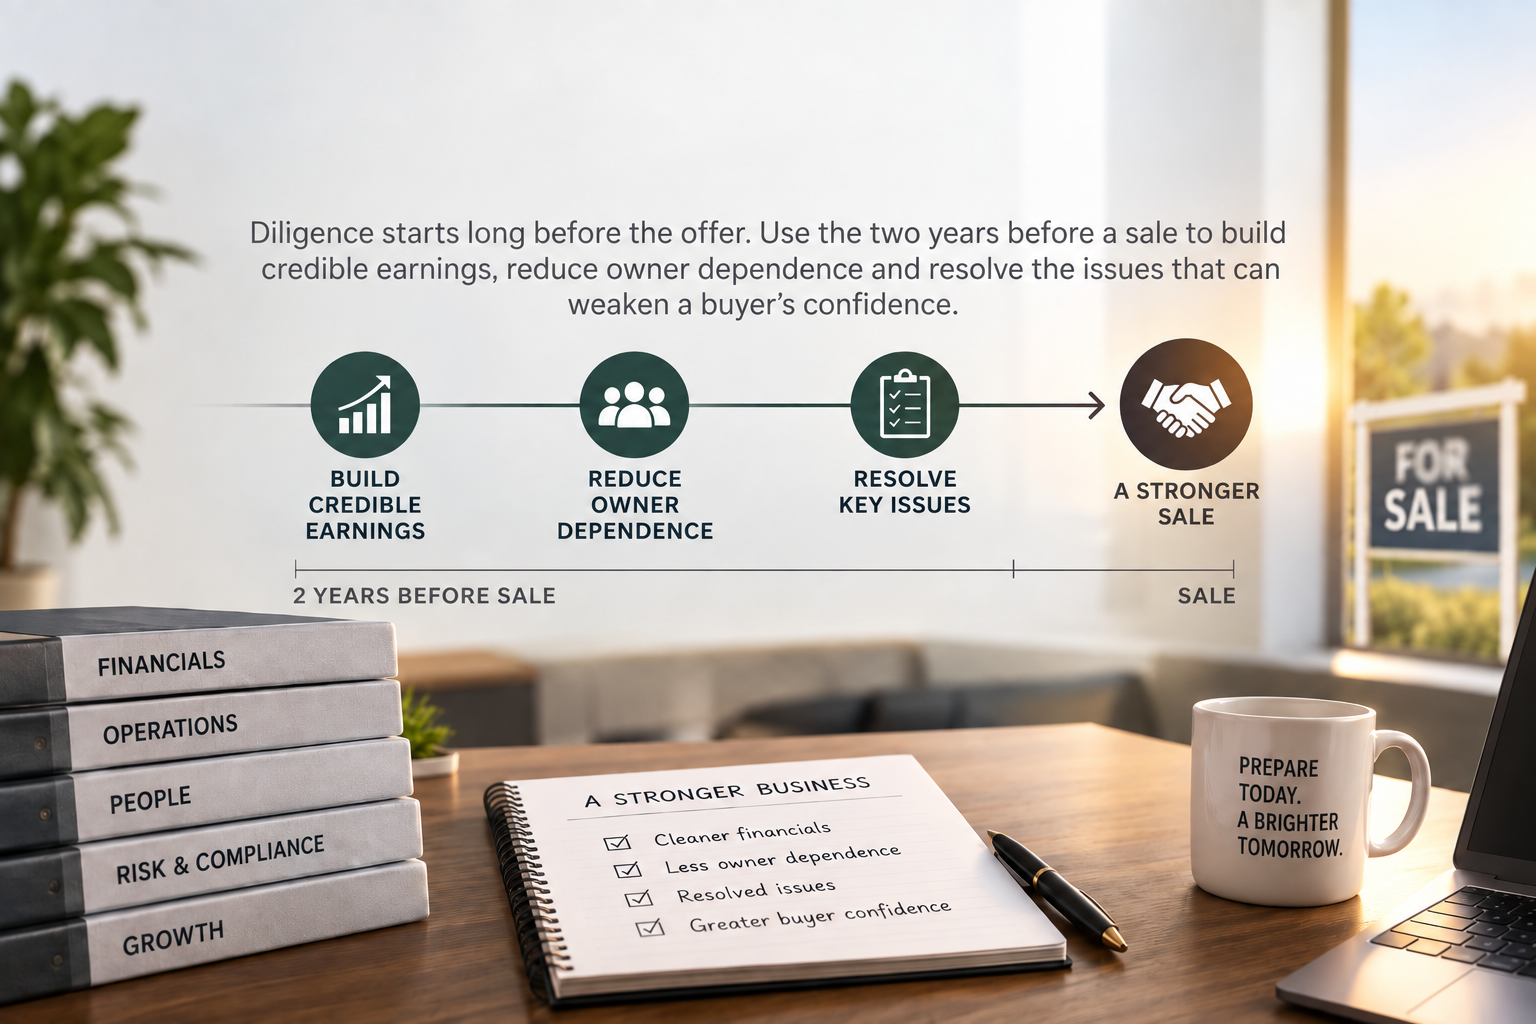
Diligence starts long before the offer. Use the two years before a sale to build credible earnings, reduce owner dependence and resolve the issues that can weaken a buyer’s confidence.
In short
- Buyers need to trust both your reported earnings and the business’s ability to sustain them without you.
- Clean up weaknesses that need a trading history to prove improvement before tackling presentation.
- A higher headline offer is not always a better outcome: deal terms determine how much value you receive and when.
Two years before a sale, most owners are still focused on winning work, hiring people and delivering results. Those priorities do not disappear when you start preparing for an exit. The difference is that you need to look at the business through a buyer’s eyes as well.
Formal due diligence usually comes later, but the evidence a buyer will examine is being created now. Your accounts, customer relationships, management decisions and contracts will tell a story that a polished sale presentation cannot easily change. The aim is not to make the business look perfect. It is to make its performance understandable, its risks manageable and its future less dependent on you.
Buyers are testing whether the earnings will travel
A buyer is acquiring future benefits, not rewarding you for past effort. They want to know whether customers will stay, people will deliver and cash will arrive after ownership changes. Strong recent profit matters, but so does the explanation behind it: was it repeatable trading, a temporary pricing advantage or one unusually large project?
Different buyers will weigh these questions differently. A trade buyer may value customer access or a specialist capability. A financial buyer may place more weight on standalone management and predictable cash generation. In either case, uncertainty can affect valuation, payment timing, retention arrangements or whether the transaction proceeds.
First, make the numbers easy to trust
Start with a consistent monthly reporting pack: profit and loss, balance sheet, cash flow and a small set of operating measures. Reconcile the underlying records and explain significant movements. A buyer should be able to follow the route from reported revenue to profit and then to cash without relying on your memory.
Look closely at revenue recognition, overdue debt, stock valuation, accrued costs and work in progress where relevant. Inconsistent treatment can undermine confidence even when the underlying business is sound. Also separate genuinely exceptional costs from expenses required to keep trading. Owners’ proposed profit adjustments are likely to be challenged, particularly if a supposedly one-off cost recurs.
If you perform a substantial operational role, assess the realistic cost of replacing that work. Removing your remuneration from an earnings calculation without allowing for replacement management can overstate maintainable profit. Equally, distinguish personal or non-business expenditure clearly rather than leaving a buyer to untangle it.
Track working capital through the year, not just at year-end. Buyers will want to understand how much cash is tied up in receivables, stock and supplier payments during normal trading. Profit growth that continually consumes cash raises a different set of questions from growth that funds itself.
Show why customers will keep buying
Analyse revenue and gross margin by customer, service or product, and identify concentration. A large customer is not automatically a problem. The risk depends on the strength of the relationship, contract terms, profitability, renewal prospects and how easily that customer could leave.
Distinguish contracted recurring revenue from repeat purchasing and uncommitted pipeline. Each can be valuable, but they offer different levels of visibility. Support your description with renewal history, customer retention, order patterns and evidence of how sales opportunities convert.
Where a key account only deals with you, introduce a credible second relationship now. Where agreements are informal, consider whether appropriate written terms would improve clarity. Review important contracts with legal advisers, including termination, assignment and change-of-control provisions. Do not assume that an agreement will continue unchanged after a sale.
Build a business that can operate without your intervention
Map the decisions, relationships and knowledge that sit with you alone. This may include pricing exceptions, supplier negotiations, technical approvals, recruitment or resolving customer complaints. The question is not whether you are important. It is whether your departure would interrupt normal trading.
Give capable managers defined authority, useful reporting and clear accountability. Document critical processes where a handover would otherwise rely on informal knowledge. Then test the arrangements: can the team run a reporting cycle, handle a service failure or negotiate a renewal without you stepping in?
A management structure on paper is weaker evidence than a team that has delivered consistently. Review key-person exposure beyond the owner too. A business can become less dependent on its founder while remaining vulnerable to the departure of one technical specialist or sales leader.
Prioritise work that takes time to prove
Not every weakness deserves the same investment. Prioritise issues by their likely effect on buyer confidence and the time needed to demonstrate improvement. Use the sequence below as a starting point, rather than a fixed timetable.
| Area | Start early | Evidence to build |
|---|---|---|
| Financial reporting | Resolve inconsistent accounting and slow monthly reporting. | Reconciled accounts, clear adjustments and credible forecasts. |
| Customer resilience | Address fragile relationships, concentration and unclear terms. | Renewals, margin quality and relationships beyond the owner. |
| Management | Delegate meaningful decisions and close capability gaps. | Sustained delivery without routine owner intervention. |
| Legal and operational records | Identify missing agreements, ownership questions and unresolved disputes. | Complete records and documented resolution or mitigation. |
| Sale preparation | Clarify objectives and assess likely buyer requirements. | A consistent business narrative supported by accessible documents. |
Alongside these improvements, organise the documents a buyer will expect to inspect: statutory and management accounts, material contracts, employment records, property arrangements, insurance and evidence of intellectual property ownership. Include relevant compliance records and known disputes. Professional review should follow the business’s actual risks; a generic folder checklist is not a substitute for resolving substantive issues.
Use the next 90 days to establish your baseline
Commission a focused readiness review with your finance lead and appropriate external advisers. Ask them to identify the few issues most likely to affect value, terms or completion. Assign each an owner, a deadline and an observable outcome. For example, ‘reduce founder dependence’ becomes ‘the operations lead owns weekly delivery decisions and reports performance without founder intervention’.
Clarify your own objectives at the same time: when you want to leave, whether you would retain an investment, how long you would support a handover and how much payment uncertainty you can accept. These preferences help distinguish an attractive headline valuation from a deal that actually suits you.
Review progress quarterly while continuing to invest sensibly in the business. Cutting essential expenditure to flatter short-term earnings can weaken the asset you intend to sell. Two years gives you time not just to fix problems, but to demonstrate that the fixes work. That evidence is the strongest preparation you can take into a sale process.
About the author
Azadeh Aghajani, FCA
Founder of Simora Advisory. Twenty years in senior finance — CFO of two private-equity-backed payments companies, CFO of Asset Servicing at BNY, and FP&A and pricing leadership at TSYS, Barclays and RBS. She qualified as a Chartered Accountant at PwC.