Reading a variance report in one page
Turn the gap between plan and actual performance into a clear account of what happened, what it means and what the team should do next.
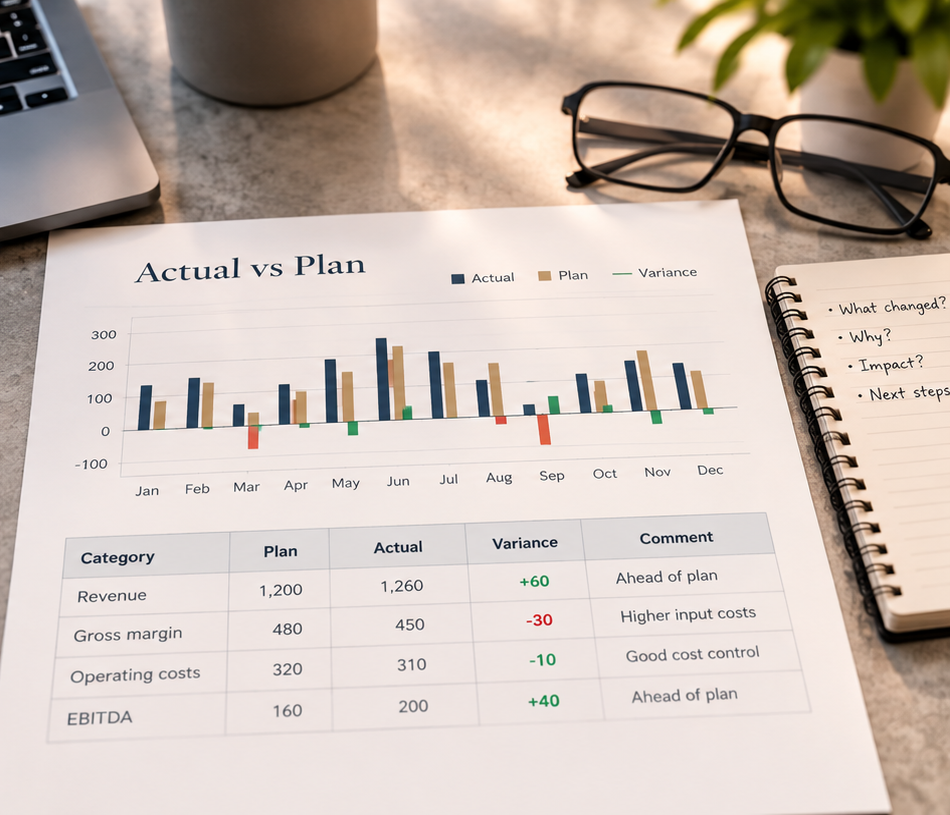
A variance report compares actual performance with a budget or forecast. But a list of differences is not a story the team can act on. Your one-page commentary should answer three questions: what mattered this month, why did it happen, and what changes now?
Start with the comparison, not the spreadsheet
State which plan you are comparing against: the original budget or a named version of the forecast. The budget shows performance against the original ambition; the latest forecast shows whether recent expectations were realistic. Switching between them without explanation makes the story unreliable.
Check that the month is complete enough to interpret. Missing supplier invoices, incorrect cut-off or unrecorded revenue can look like operating performance. Use plain labels such as “£12,000 below plan” rather than expecting everyone to understand whether a positive variance is good or bad.
Choose the two or three differences that matter
Prioritise differences that affect profit, cash or an important operating decision. Show the pound value alongside the percentage: a large percentage on a tiny cost line may matter less than a small margin movement across all sales. Check the year-to-date position too; repeated small misses can be more significant than one unusual month.
Then move from the accounting line to the operational cause. Revenue may be down because fewer units sold, prices fell, the sales mix changed or delivery slipped. Payroll may be below plan because recruitment is late, not because the team has become more productive. “Sales were below budget” describes the result; it does not explain it.
Connect the result to a decision
For each major driver, explain the result, cause, likely persistence and response. Separate confirmed facts from assumptions. Where the cause is unclear, assign an investigation rather than presenting a confident explanation.
Illustrative commentary
“Revenue was £30,000 below forecast. Of this, £20,000 relates to a delivery moved into next month; the customer has confirmed the revised date. The remaining £10,000 reflects fewer new orders than planned. The sales lead will review conversion by Friday and update next month’s order assumptions. Finance will assess the cash effect of later invoicing.”
This gives the team something to test and do. It also avoids assuming that all missed sales will return next month. Explain profit and cash separately: later invoicing may delay receipts, while lower revenue can have very different profit effects depending on which costs remain.
Use a final one-page check
0 of 5 complete
Keep the detailed report available behind the page. The commentary has done its job when a non-finance colleague can explain the month and knows what they are expected to do next.
About the author
Azadeh Aghajani, FCA
Founder of Simora Advisory. Twenty years in senior finance — CFO of two private-equity-backed payments companies, CFO of Asset Servicing at BNY, and FP&A and pricing leadership at TSYS, Barclays and RBS. She qualified as a Chartered Accountant at PwC.